
Investing a lump sum of ₹5 lakh can be an important move towards achieving long-term financial goals. However, choosing the right investment avenues can be confusing, particularly with several options available, such as stocks, mutual funds, fixed deposits, gold, and bonds.
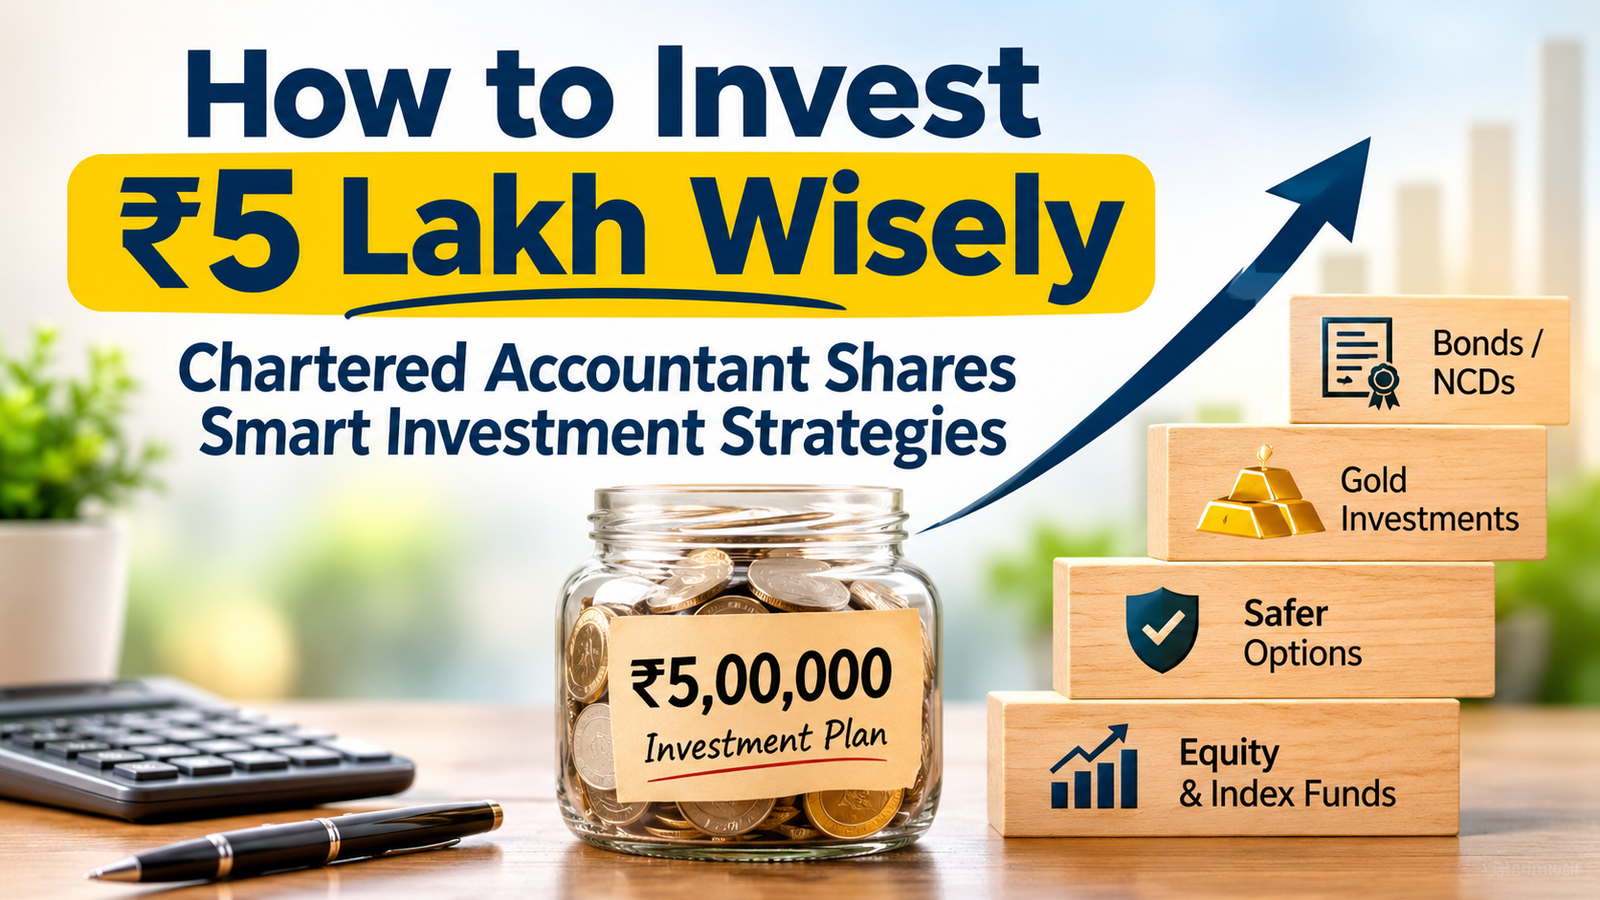
A recent investment strategy shared by Chartered Accountant Srishti Gosavi, as reported by NDTV on November 18, 2026, highlights that building wealth is not just about earning money but also about allocating and managing it wisely. Through a social media video, she suggested dividing a ₹5 lakh corpus across equity investments, relatively safer options, gold, and income-generating instruments.
However, she emphasised that her allocation strategy reflected her personal approach and should not be considered a one-size-fits-all recommendation. The ideal way to invest ₹5 lakh depends on an individual’s age, financial responsibilities, emergency fund, investment horizon, and risk appetite. Let’s explore how to invest ₹5 lakh wisely and the key factors to consider before selecting suitable investment options.
How Does a Chartered Accountant Recommend Investing ₹5 Lakh?
CA Srishti Gosavi suggests dividing a ₹5 lakh investment corpus among four broad asset categories to create a balanced portfolio. Her proposed allocation is intended for individuals below 50 years of age who do not have specific financial dependants.
The suggested distribution is as follows:
- 40–50% towards equity investments
- 10–20% in relatively safer investment options
- 10–20% in gold and gold-related investments
- 10–20% in income-generating instruments
This approach focuses on portfolio diversification by spreading the investment across different asset classes instead of committing the entire ₹5 lakh to a single financial product.
What Are the Recommended Investment Options?
1. Allocate 40–50% to Equity and Index Funds for Long-Term Wealth Creation
CA Srishti Gosavi recommended investing around 40–50% of the ₹5 lakh corpus in equity, which translates to approximately ₹2 lakh to ₹2.5 lakh. Equity investments can help build long-term wealth, although they are subject to market risks.
Investors can explore individual stocks or equity mutual funds based on their knowledge and risk appetite. For beginners who may not be comfortable selecting individual stocks, index funds can be a suitable option to consider. These mutual funds track market indices such as the Nifty 50 or Sensex by investing in the companies included in the respective indices.
Index funds offer diversification across multiple companies, broad market exposure and a relatively simple investment approach.
2. Allocate 10–20% to Relatively Safer Investment Options
CA Srishti Gosavi suggested investing around 10–20% of the ₹5 lakh corpus, or approximately ₹50,000 to ₹1 lakh, in relatively safer options such as fixed deposits (FDs), debt mutual funds, and arbitrage funds.
– Fixed Deposits (FDs): Suitable for investors seeking predictable interest income and relatively stable returns.
– Debt Mutual Funds: These funds invest in fixed-income instruments such as government securities, corporate bonds, and money market instruments. However, their returns are subject to interest rate, credit, and liquidity risks.
– Arbitrage Funds: These funds aim to benefit from price differences between the cash and derivatives markets. Although generally considered relatively lower-risk than equity funds, they do not offer guaranteed returns.
3. Allocate 10–20% to Gold for Portfolio Diversification
CA Srishti Gosavi recommended investing around 10–20% of the ₹5 lakh corpus, or approximately ₹50,000 to ₹1 lakh, in gold-related investments. Gold can help diversify a portfolio as its price movements may differ from those of equity and debt investments.
Instead of buying physical gold jewellery, investors can explore the following options:
- Gold ETFs: These market-linked products track domestic gold prices and allow investors to invest in gold without physically holding or storing it.
- Gold Mutual Funds: These funds generally invest in Gold ETFs, offering investors an alternative way to gain exposure to gold without directly purchasing ETF units.
- Gold Stocks: Shares of companies involved in gold mining, processing, or jewellery businesses can provide indirect exposure to the gold sector.
The key is to use gold as a diversification tool rather than concentrating the entire investment portfolio in a single asset class.
4. Allocate 10–20% to Income-Generating Investments
The remaining 10–20% of the ₹5 lakh corpus, amounting to approximately ₹50,000 to ₹1 lakh, can be invested in income-generating instruments such as bonds and non-convertible debentures (NCDs).
- Bonds: Bonds are basically debt instruments in which investors lend money to public/ private companies or the Government to get interest payments. Before investing, check the issuer’s credit rating, interest rate, maturity period, and repayment terms.
- Non-Convertible Debentures (NCDs): Companies issue NCDs to raise funds, offering investors interest payments as per the specified terms. However, they carry credit and liquidity risks, so investors should review the company’s financial position, credit rating, security status, and offer document before investing.
How can You Distribute a ₹5 Lakh Investment Across Different Asset Classes?
Using the allocation ranges shared by CA Srishti Gosavi, investors can consider the following illustrative portfolio to understand how a ₹5 lakh corpus could be distributed across different investment categories.
| Investment category | Allocation | Investment amount |
| Equity / Index Funds | 45% | ₹2,25,000 |
| Safer investment options | 15% | ₹75,000 |
| Gold investments | 20% | ₹1,00,000 |
| Bonds / NCDs | 20% | ₹1,00,000 |
| Total | 100% | ₹5,00,000 |
Note: This is an indicative allocation based on the percentage ranges suggested by the CA. It is an illustrative example, not her exact recommended portfolio or personalised investment advice.
What Factors Should You Consider Before Investing ₹5 Lakh?
Selecting suitable investment products is important, but investors should also evaluate their financial needs and circumstances before deciding how to allocate ₹5 lakh. Here are some key factors to keep in mind:
1. Prioritise an Emergency Fund
Before investing in market-linked products, set aside an emergency fund to manage unexpected expenses such as medical bills, job loss, or urgent household needs. RBI’s financial education guidance recommends maintaining savings equivalent to at least three months of living expenses.
2. Assess Your Risk Appetite
Different investments carry different risks. Equity funds are exposed to market volatility, debt instruments carry credit and interest rate risks, and gold prices can fluctuate. Evaluate your ability to handle potential losses before investing. SEBI’s Riskometer can help assess the risk level of mutual fund schemes.
3. Set Your Investment Horizon
Your investment duration should influence your asset allocation.
- Short-term goals: Prioritise liquidity and capital protection.
- Medium-term goals: Consider a balanced investment mix.
- Long-term goals: Consider greater equity exposure, depending on your risk appetite.
Avoid putting money needed soon into highly volatile investments.
4. Repay High-Interest Debt
Consider clearing expensive outstanding debt, such as credit card balances and high-interest personal loans, before investing the entire amount. Their interest costs may exceed the returns generated by many investment options.
5. Diversify Your Portfolio
Avoid putting the entire ₹5 lakh into a single stock or asset class. Spreading investments across equity, debt, and gold can help manage concentration risk, although diversification does not eliminate market risks or guarantee returns.
6. Understand the Tax Implications
Tax treatment varies across investment products. FD interest is generally taxable as per the applicable income-tax slab, while capital gains from equity funds, debt funds, and gold investments follow different tax rules. Check the applicable tax provisions before making investment decisions.
Investment Mistakes to Avoid When Putting ₹5 Lakh to Work
Poor financial decisions can affect even a carefully planned investment portfolio. Investors should be mindful of the following common mistakes:
- Investing without clear goals: Define your financial objectives before deciding where to invest.
- Chasing high returns: Avoid products promising unusually high returns without understanding the associated risks.
- Overinvesting in equities: Putting the entire corpus into stocks or equity funds can expose your portfolio to higher market volatility.
- Neglecting emergency savings: Keep sufficient funds accessible instead of locking away all your money in investments.
- Blindly following social media tips: Research investment products and assess their suitability before making decisions.
- Overlooking costs and taxes: Account for expense ratios, transaction charges and applicable taxes, as they can reduce actual returns.
- Skipping portfolio reviews: Monitor your investments regularly and rebalance them when your financial goals or risk appetite change.
Final Thoughts
Investing ₹5 lakh effectively takes more than chasing high returns; it requires setting clear financial goals, managing risk, and diversifying across suitable asset classes. CA Srishti Gosavi’s suggested approach highlights the importance of balancing equity, safer investments, gold, and income-generating instruments. However, the ideal allocation varies based on an individual’s financial responsibilities, emergency savings, risk appetite, and investment horizon. Carefully assess your financial situation and choose investments that align with your long-term goals.
Disclaimer: This Blog is for educational purposes only, and Market-linked investments are subject to risks. Read all relevant documents carefully and consult a qualified financial adviser before investing. Assess your financial needs and risk appetite to choose investments that align with your goals and make effective use of your ₹5 lakh corpus.
Sources: NDTV